

 17 hours ago
3

Introduction
France occupies a distinctive position in the European economy. It is one of the Eurozone’s largest economies, a central political actor in the European Union, and a state whose public sector, welfare system, and pension arrangements remain unusually extensive by international standards. Yet these institutional strengths have become sources of fiscal pressure. Successive shocks like the COVID-19 pandemic, the energy-price crisis following Russia’s invasion of Ukraine, and slower post-pandemic growth expanded deficits and debt while limiting the government’s room for maneuver (International Monetary Fund [IMF], 2023, 2024).
The central argument of this article is that France’s economic strain results from the convergence of three factors.
First, public debt has risen beyond 115% of GDP, driven by high structural spending, social programs, pensions, and emergency fiscal responses.
Second, as a Eurozone member, France lacks autonomous control over interest rates and cannot devalue its currency, leaving fiscal policy as the principal adjustment mechanism.
Third, persistent deficits and reform attempts have intensified domestic polarization, worsened living-cost pressures, and produced legislative deadlock. Together, these conditions have weakened the capacity of French governments to implement durable economic strategy.
.

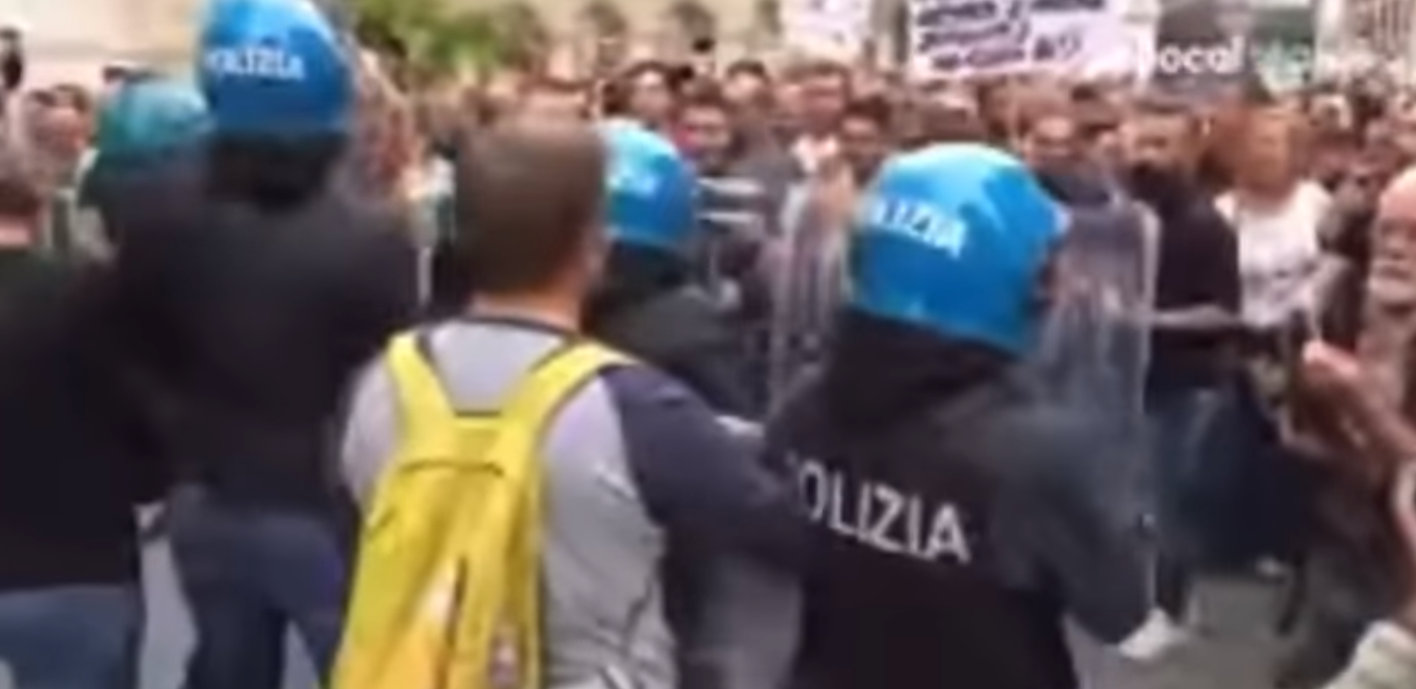
Manifestation on 6 October 2026 in Paris. (CC BY-SA 4.0)
.
The Debt Burden
France’s public finances deteriorated sharply after 2020. According to the French national statistics institute, general-government debt stood at 114.9% of GDP in 2020, fell somewhat during the recovery, and then rose again to 112.6% in 2024 and 115.7% in 2025 (INSEE, 2026a). The 2025 debt level corresponds to a stock of public liabilities of roughly €3.3 trillion, a scale that makes even modest increases in borrowing costs consequential for the annual budget (RFI, 2025).
The debt trajectory reflects both cyclical emergencies and structural spending commitments. During the pandemic, France deployed large-scale support for firms, workers, and public services. Subsequently, the energy crisis produced another major fiscal response: price shields, energy checks, fuel support, and cash transfers intended to protect household purchasing power. The IMF estimated that French energy-related support reached approximately 2% of GDP in 2021–2022, with much of it delivered through broad, relatively untargeted measures (IMF, 2023). These interventions cushioned households and firms, but they also narrowed fiscal space and widened France’s debt gap relative to other Eurozone economies (IMF, 2023).
The deeper difficulty is that France’s fiscal problem is not merely a temporary consequence of crisis spending. General-government expenditure remains around 56% to 59% of GDP in recent years, substantially above the Eurozone average, reflecting high public employment, health and social protection spending, and pension commitments (IMF, 2024). Pension expenditure is especially politically sensitive because the system is closely tied to widely valued social expectations about retirement age, contribution levels, and intergenerational fairness. The 2023 reform raising the legal retirement age from 62 to 64 was justified by the government as necessary for the system’s long-term viability, but it became one of the most contested policy measures of Macron’s presidency (Reuters, 2023a, 2023b).
Debt persistence also has financial consequences. When investors perceive that a government may struggle to pass credible consolidation measures, they demand higher yields on sovereign bonds. This was visible in late 2024, when French borrowing costs rose sharply amid uncertainty over the 2025 budget and the government’s ability to reduce the deficit (Cambridge University Press, 2026). Higher yields then increase debt-service costs, potentially requiring further borrowing and making consolidation more difficult—a classic fiscal-feedback loop.
Monetary Constraints in the Eurozone
France’s second constraint is institutional. Since adopting the euro, France no longer conducts an independent monetary policy. Interest rates are set by the European Central Bank (ECB) for the euro area as a whole, not according to the specific cyclical or fiscal conditions of any individual member state. This arrangement provides important benefits like price stability, lower transaction costs, deeper financial integration, and protection from unilateral currency instability but it also removes tools that countries with sovereign currencies can use during downturns or competitiveness crises.
Two instruments are especially relevant. First, France cannot independently lower interest rates to stimulate domestic demand or reduce the burden of public borrowing. If French growth weakens while inflation or financial conditions elsewhere in the euro area warrant tighter ECB policy, France must absorb the common monetary stance. Second, France cannot devalue the euro to improve export competitiveness. A nominal depreciation could, in principle, make French goods cheaper abroad and support export-led adjustment; within the Eurozone, that option is unavailable.
This does not mean that Eurozone membership is economically harmful in itself. Rather, it changes the adjustment mechanism available to member states. A country outside the monetary union may respond to external shocks through exchange-rate movement and independent monetary policy. A Eurozone member must instead rely more heavily on internal adjustment: wage moderation, productivity growth, labor-market reform, fiscal consolidation, or structural changes in taxation and public spending. For France, whose economy depends heavily on domestic demand and public services, this makes fiscal and structural reform more central and more politically difficult.
The constraint is particularly important because France’s competitiveness problems cannot be solved quickly through currency movements. If French firms lose price competitiveness relative to German, Dutch, or southern European competitors, adjustment must occur through relative unit labor costs, investment, innovation, and productivity. These are slower channels. In the short run, therefore, Eurozone membership magnifies the importance of sound public finances: a state with high debt and weak growth has fewer ways to offset shocks without relying on deficit spending.
Fiscal Consolidation and Political Polarization
The third factor is political. Reducing a deficit requires either higher revenue, lower spending, or both. In France, each option carries substantial distributional and ideological conflict. Tax increases may be resisted by households and firms already affected by inflation; spending cuts threaten public services, welfare benefits, and public employment; pension reform directly affects retirement expectations for millions of workers. Because France’s fiscal model is built around a broad social state, consolidation cannot be presented as a narrow technical exercise. It becomes a conflict over the social contract itself.
This conflict became especially visible during the 2023 pension debate. The government’s proposal to raise the retirement age from 62 to 64 provoked nationwide strikes and demonstrations, with unions mobilizing hundreds of thousands and, by some official estimates, more than one million participants (Reuters, 2023a, 2023b). The reform was ultimately adopted through the constitutional Article 49.3 procedure, allowing the government to pass legislation without a vote in the National Assembly. Although constitutionally lawful, this method deepened the perception that major economic reforms were being imposed without adequate democratic deliberation.
The 2024–2025 budget crisis extended this pattern from social policy to the core of state finance. Prime Minister Michel Barnier proposed a 2025 budget containing approximately €40 billion in spending cuts and €20 billion in tax increases, aiming to address an excessive deficit and reassure European institutions and financial markets (Cambridge University Press, 2026). However, the government lacked a parliamentary majority. The Rassemblement National and the left-wing New Popular Front both rejected austerity, and their combined opposition brought down Barnier’s government in a no-confidence vote on 4 December 2024 (BBC News, 2024; Cambridge University Press, 2026).
The consequences were not merely symbolic. For a period, France operated under a “special law” regime that extended prior expenditure rules, allowing the state to continue functioning but delaying a comprehensive budget settlement (Cambridge University Press, 2026). This institutional uncertainty weakened the credibility of fiscal planning and made it harder to meet deficit targets. Fitch Ratings (2024) warned that the fragmented National Assembly made compromise on fiscal consolidation unlikely and projected that continued deficits above 5% of GDP could push debt toward 118.5% of GDP by 2028.
Living Costs and Social Pressure
Economic strain has also been experienced socially. Inflation, especially energy and food-price increases after 2022, reduced purchasing power and heightened public sensitivity to taxation, wages, pensions, and public-service provision. The French government responded with substantial support measures, including energy price shields and household transfers, which moderated the immediate impact of energy inflation but added to fiscal costs (Banque de France, 2022; IMF, 2023).
This created a political dilemma. Protecting purchasing power was necessary to prevent hardship and preserve social peace, yet the methods used were expensive and difficult to target precisely. The IMF (2023) noted that France’s energy-price support was comparatively costly and distortionary because much of it subsidized consumption across income groups rather than concentrating assistance on vulnerable households. Thus, measures designed to address a social emergency contributed to the fiscal problem that later governments needed to solve.
Pension reform intensified this tension. In a period of high living costs, asking workers to remain in employment longer was widely perceived as a loss of purchasing power and security, even if the government framed it as necessary for long-term sustainability. The result was a collision between macroeconomic necessity and distributive fairness: fiscal consolidation demanded sacrifice, but the burden of sacrifice was contested.
.

Day of mobilization for high school students in Perpignan (CC BY 4.0)
.
Legislative Deadlock and Government Instability
France’s political institutions were designed to provide strong executive authority, but the parliamentary fragmentation that followed the 2024 snap elections has limited that capacity. The National Assembly became divided among three principal blocs: the presidential centrist alliance, the left-wing New Popular Front, and the Rassemblement National. However, none of which possessed a stable majority or a strong incentive to cooperate (House of Commons Library, 2025; Heinrich Böll Foundation, 2025).
This fragmentation has turned budget-making into a recurring test of governmental survival. The fall of Barnier’s government demonstrated that even a conventional consolidation budget could unite ideological opponents against it. Later instability, including the brief collapse of the Lecornu government in 2025, reinforced the impression that France’s problem was not simply one government’s weakness but a systemic difficulty in forming durable parliamentary coalitions (UK in a Changing Europe, 2025).
The economic consequence is a credibility problem. Financial markets, European institutions, and domestic actors require a credible medium-term plan for reducing deficits and stabilizing debt. But a government that cannot reliably pass a budget cannot credibly commit to such a plan. Conversely, a government that attempts forceful consolidation through executive procedures risks social protest and parliamentary rebellion. France is therefore caught between fiscal necessity and political feasibility.
Interacting Causes
The three factors discussed above should not be treated as separate problems. They form a feedback system. High public spending and repeated crisis responses raise debt. High debt limits fiscal flexibility and increases sensitivity to borrowing costs. Eurozone membership prevents monetary or exchange-rate offset, making fiscal adjustment more important. But fiscal adjustment is politically divisive in a high-spending social democracy. Political polarization then blocks reform, which prolongs deficits, weakens credibility, and may raise borrowing costs further. The loop is completed when higher debt-service costs make additional consolidation necessary.
.

.
This interaction explains why France’s crisis is more serious than a temporary budget shortfall. Even if the deficit declines, as it did from 5.8% of GDP in 2024 to 5.1% in 2025, debt can continue rising if growth remains weak and interest costs are high (INSEE, 2026b; Reuters, 2026). Fiscal improvement is therefore necessary but insufficient: France also needs a politically sustainable settlement over the size and financing of its social state.
Policy Implications
A credible response would need to combine fiscal consolidation with growth-enhancing reform. Pure austerity risks deepening stagnation and social resistance; continued deficit spending risks market pressure and further debt accumulation. The more plausible path involves targeted rather than blanket measures: phasing out broad energy subsidies, protecting low-income households, improving tax collection and efficiency, reforming public expenditure without undermining essential services, and pursuing productivity-enhancing investment.
Pension policy remains central because it affects both long-run expenditure and social legitimacy. Any durable reform would need broader political negotiation, gradual implementation, and compensatory measures for workers in physically demanding occupations or with interrupted careers. The lesson of 2023 is not that pension reform is impossible, but that reforms imposed with limited parliamentary consent are likely to generate enduring opposition.
Institutional reform may also be necessary. France’s current impasse reflects not only ideological disagreement but a parliamentary structure in which no bloc can govern alone and coalition-building norms remain weak. A more stable fiscal framework would require either the emergence of a governing majority willing to compromise or procedural arrangements that encourage negotiated budgets rather than repeated reliance on Article 49.3.
Conclusion
France’s economic strain arises from the interaction of high public debt, constrained monetary autonomy, and political fragmentation. The debt burden reflects both deliberate social commitments and emergency responses to the pandemic and energy crisis. Eurozone membership removes independent monetary and exchange-rate tools, making fiscal policy the principal adjustment channel. Yet fiscal adjustment is politically explosive in a country whose welfare state, pension system, and public services are central to its social model.
The result is a governance dilemma: France needs credible consolidation, but the political system currently struggles to produce it. Without a negotiated settlement on spending, taxation, pensions, and growth policy, budget crises and governmental instability are likely to recur. France’s economic future therefore depends not only on arithmetic that reduces deficits and stabilizes debt but on reconstructing the political capacity to agree on how the French social model should be financed in a more constrained European and global environment.
*
Click the share button below to email/forward this article. Follow us on Instagram and X and subscribe to our Telegram Channel. Feel free to repost Global Research articles with proper attribution.
Prof. Ruel F. Pepa is a Filipino philosopher based in Madrid, Spain. A retired academic (Associate Professor IV), he taught Philosophy and Social Sciences for more than 15 years at Trinity University of Asia, an Anglican university in the Philippines. He is a Research Associate of the Centre for Research on Globalization (CRG).
References
Banque de France. (2022). Macroeconomic projections France—June 2022. Macroeconomic projections – June 2022 | Banque de France
BBC News. (2024, December 4). Barnier vote: Why France’s turmoil is grave concern for Europe. Barnier vote: Why France’s turmoil is grave concern for Europe
Cambridge University Press. (2026). France: Political developments and data for 2024. European Political Data Yearbook. France: Political Developments and Data for 2024 | Political Data Yearbook | Cambridge Core
European Council. (2023). Council recommendation on the 2023 national reform programme of France and delivering a Council opinion on the 2023 stability programme of France [SWD(2023) 610 final]. download
Fitch Ratings. (2024, December 6). French government collapse deepens political and budgetary uncertainty. French Government Collapse Deepens Political and Budgetary Uncertainty
Heinrich Böll Foundation. (2025, October 15). Three questions on the political crisis in France. 3 Questions on the political crisis in France to Marc Berthold | Heinrich Böll Stiftung | Brussels office – European Union
House of Commons Library. (2025, July 28). France: Recent political developments and the 2024 National Assembly elections (Research Briefing CBP-10112). France: recent political developments and the 2024 National Assembly elections – House of Commons Library
International Monetary Fund. (2023, January 30). IMF executive board concludes 2022 Article IV consultation with France. IMF Executive Board Concludes 2022 Article IV Consultation with France
International Monetary Fund. (2024, July 13). IMF executive board concludes 2024 Article IV consultation with France. IMF Executive Board Concludes 2024 Article IV Consultation with France
INSEE. (2026a, May 29). General government accounts in 2025 (Insee Première No. 2106). General Government Accounts in 2025 – Insee Première – 2106
INSEE. (2026b, March 27). In 2025, the public deficit stands at 5.1% of GDP. In 2025, the public deficit stands at 5.1% of GDP, the public debt at 115.6% of GDP – Informations rapides – 78 | Insee
Reuters. (2023a, February 11). France protests look to test government’s resolve on pension reforms. France protests look to test government’s resolve on pension reforms | Reuters
Reuters. (2023b, March 23). Violence hits France in day of anger over Macron’s pension changes. Violence hits France in day of anger over Macron’s pension changes | Reuters
Reuters. (2026, March 27). France rules out broad energy aid despite lower deficit. France rules out broad energy aid despite lower deficit | Reuters
RFI. (2025, September 2). France’s debt: How did we get here, and how dangerous is it? France’s debt: how did we get here, and how dangerous is it? – RFI
UK in a Changing Europe. (2025, October 22). States of anxiety: France’s political crisis in perspective. States of anxiety: France’s political crisis in perspective – UK in a changing Europe
Featured image: Manifestation on 17 October 2026 in Paris. (CC BY-SA 4.0)
Global Research is a reader-funded media. We do not accept any funding from corporations or governments. Help us stay afloat. Click the image below to make a one-time or recurring donation.







.png)

.jpg)

 English (US) ·
 French (CA) ·